
As discussions to institutionalise won-denominated stablecoins move into the final stage, how broadly to allow issuers has emerged as a key issue.
According to the financial sector on Oct. 26, the government and related agencies are continuing talks over issuer eligibility for won stablecoins, reserve assets and the redemption system to be included in the Digital Asset Framework Act.
One option under discussion would allow stablecoin issuance centred on a consortium in which banks secure a stake of at least "50 percent plus one share". Detailed issuance structure has not been finalised.
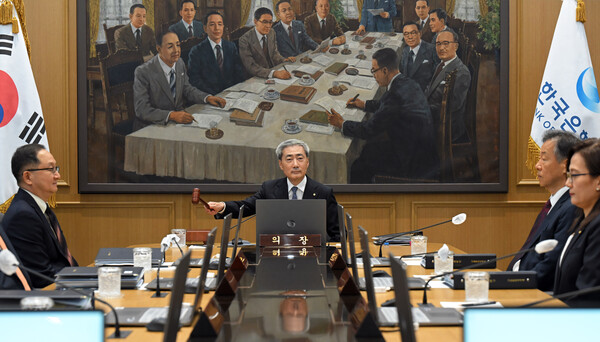
The Bank of Korea supports introducing private won stablecoins. Bank of Korea Governor Hyun Song Shin (신현송) said at a parliamentary audit of the National Assembly's Fiscal and Economic Planning Committee on Oct. 12 that he was "basically in favour" and that the approach would be to form a consortium led by private banks, as agreed with the government.
The main reason the central bank is stressing a bank-centred structure is that if won stablecoins spread beyond being a simple digital asset to become a means of payment, they could directly affect financial markets and monetary policy.
In particular, if the scale of stablecoins grows, large redemption demands could increase financial market volatility through reserve-asset sales or capital outflows. Shin also said on related risks, "We will cooperate with authorities to prepare for potential risks."
Reserve assets and redemption rights are also key tasks. For a stablecoin to maintain a value of "1 won equals 1 coin", the issuer must secure sufficient reserve assets to meet users' redemption requests.
In the institutional design process, discussions are expected to cover which assets will be recognised as reserve assets, how far to guarantee users' right to redeem in won, and how to set liquidity and capital requirements for issuers.
A bank-centred approach has the advantage of leveraging the existing financial supervisory framework. Banks are already subject to financial authorities' regulation on capital adequacy and liquidity, anti-money laundering (AML) and internal controls, making it relatively easier to manage risks arising from stablecoin issuance.
On the other hand, some argue that if non-bank participation is overly restricted, it could dampen technology development and service competition in stablecoins.
Fintech and digital-asset companies have strengths in blockchain technology, user bases and payment and distribution infrastructure. But if issuance is limited to consortia in which banks hold a majority stake, it will be difficult for them to secure business leadership.
As domestic discussions drag on, won-pegged stablecoins have already emerged overseas. KRWQ, issued abroad, is designed to be pegged 1-to-1 to the won and is circulating on Ethereum and Base, among others. As of Oct. 22, its market capitalisation stood at about $546,110, or about 720 million won, and is still not large.
How to divide roles between financial authorities and the central bank is also a remaining task. The Financial Services Commission must set up a market discipline framework through the Digital Asset Framework Act, including entry requirements for issuers, reserve assets, user protection, and disclosure and redemption obligations. The Bank of Korea is expected to check the impact of won stablecoins on payments and settlements, monetary policy and financial stability.
The Bank of Korea's announcement that it will not pursue a general-purpose central bank digital currency (CBDC) also intersects with won stablecoin discussions.
Shin said that since 2023 the central bank has not been reviewing a general-purpose CBDC that individuals use directly, and is 추진 Project Hangang focused on a wholesale CBDC and bank deposit tokens.
Overseas, a structure is taking hold that does not necessarily limit issuers to banks.
The United States allows not only banks but also non-bank operators that meet certain licensing requirements to issue stablecoins. Japan also allows banks, fund transfer operators and trust companies to participate in issuance. The European Union also recognises banks and electronic money institutions, among others, as issuers.
Ultimately, the key issue in South Korea is expected to focus not on choosing only one side between banks and non-banks, but on how far to apply requirements for reserve assets and redemption, capital and liquidity, and internal controls if non-bank operators are allowed to issue.
Lee Jun-ho (이준호), an analyst at Hana Securities, said the Bank of Korea has said it plans to use a wholesale CBDC as a settlement asset in a 2027 proof-of-concept on tokenised government bonds, and that using private stablecoins is not yet under consideration. He also said the likelihood has increased that the private sector and financial market infrastructure will adopt different payment instruments in the early domestic digital-asset market.
 Sangyeob Oh
yub@d-today.co.kr