
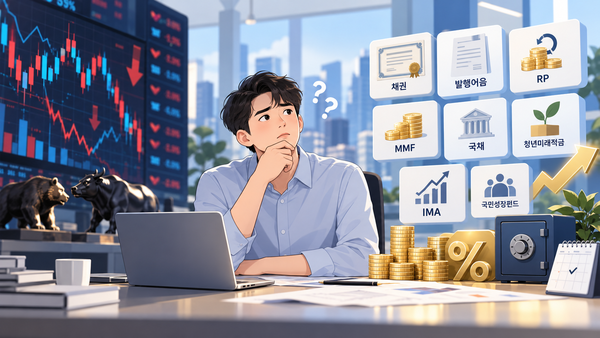
South Korea's stock market is languishing, while market interest rates remain high. Investors are shifting attention to interest-bearing products such as brokerage-issued notes, repurchase agreements (RP) and government bonds.
Experts say the current market environment allows investors to use higher interest rates to secure a certain level of interest income. They advise focusing not only on high returns but also on deciding when the money will be needed again.
Among interest-bearing products, brokerage-issued notes are instruments with maturities of up to 1 year that securities firms issue on their own credit. On-demand types make it easier to withdraw funds when needed, while fixed-term types offer relatively higher contracted yields in return for keeping money in place for a set period.
Mirae Asset Securities' yields for retail won-denominated brokerage notes, applied since Aug. 31, show an annual 2.60 percent before tax for on-demand products. Fixed-term products offer 3.05 percent for 91 to 180 days, 3.60 percent for 181 to 270 days, and 3.85 percent for 271 to 364 days and 1-year products. The 1-year product rose by 0.20 percentage point from the previous 3.65 percent.
If fixed-term products are cancelled early, yields can fall sharply. For Mirae Asset Securities, 30 percent of the contracted yield applies as an early redemption yield for holding periods of 1 to 90 days, and 50 percent for 91 to 364 days. Brokerage-issued notes are not protected by deposit insurance, and principal losses can occur depending on the issuing securities firm's credit risk.
For funds parked temporarily, investors can compare RP with money market funds (MMF). RP products involve financial firms selling bonds and agreeing to buy them back at a set price after a certain period, and are divided into on-demand and contracted types.
Hanyang Securities' RP rates, based on its disclosure effective Aug. 31, show an annual 2.80 percent before tax for on-demand products. Contracted products offer 2.90 percent for 28 to 90 days, 3.00 percent for 91 to 181 days and 3.10 percent for 182 to 365 days. If a contracted product is redeemed before maturity, an early redemption rate of 1.75 percent a year applies.
That means even if the contracted rate is higher, actual returns can be lower than on-demand products if the timing of fund use is uncertain. RP is also not covered by deposit insurance.
MMFs are performance-based funds that invest in short-term financial instruments such as short-term bonds and commercial paper. Since they do not pay a pre-set interest rate, investors need to check not only recent returns but also fees and redemption conditions.
For bonds, it is important to manage investments by matching maturities to when funds will be needed. When market interest rates rise, prices of existing bonds fall, and when rates fall, prices rise. Longer-maturity fixed-rate bonds generally show larger price swings in response to rate changes.
For investors seeking to lock in current interest rate levels for a long period, government bonds for retail investors are also an option. Early redemption can be requested after 1 year from purchase, but redeeming before maturity means the additional interest rate, compound interest and tax benefits do not apply. It is necessary to approach them mainly with funds that are not planned for use over a long period.
Integrated management accounts (IMA) have a different return structure from brokerage-issued notes or government bonds. Securities firms manage client funds in assets related to corporate finance and distribute performance to investors in a performance-based product.
For IMAs, if investors hold them to maturity, the securities firm bears an obligation to pay principal, but the products are not covered by deposit insurance. They also do not pay a fixed interest rate. Since the principal payment obligation does not apply upon early cancellation, investors need to check whether they can keep funds in place until maturity.
Reference yields or target yields presented in products also differ from fixed interest rates. Actual yields can vary depending on the securities firm's performance and fees by product.
Within the National Growth Fund, the citizen-participation growth fund, which the general public can subscribe to directly, began its second offering. It will be sold from Sept. 30 to Oct. 15 with a limit of 600 billion won. In the first week of sales, 50 percent of the total allocation was set aside for low-income people, but from Oct. 8 the remaining allocation is sold without distinguishing between low-income and general investors.
If investors meet requirements and invest through a dedicated account, they can receive income deductions of up to 18 million won depending on the investment amount. A separate tax rate of 9.9 percent applies to dividend income. It is drawing interest from investors seeking stable tax benefits rather than volatile interest income.
The product is a closed-end product with a 5-year maturity, so early redemption is not possible. Investors can sell after listing on an exchange, but liquidity could be low, and transfers within 3 years of investment could result in the clawback of an amount equivalent to the reduced tax.
Ultimately, the starting point for choosing products is when the funds will be used. If money is needed within a few months, investors should first check liquidity for on-demand brokerage notes, RP and MMFs. For funds around 1 year, they can compare after-tax yields on fixed-term brokerage notes and short-term bonds.
For longer-maturity products such as government bonds for retail investors, IMAs and the citizen-participation growth fund, it is also important to consider whether funds can be tied up for a long period in line with higher yields or tax benefits. If investors also consider the possibility of further rate increases, they can use an approach that staggers reinvestment timing by splitting maturities.
The Financial Services Commission on Oct. 1 held a financial market situation check meeting and reviewed the impact of domestic and overseas interest rate rises on financial markets. Financial authorities plan to continue monitoring related risks, seeing that continued increases in market interest rates could raise funding costs for economic agents and increase repayment burdens for vulnerable borrowers.
 Sangyeop Oh
yub@d-today.co.kr